
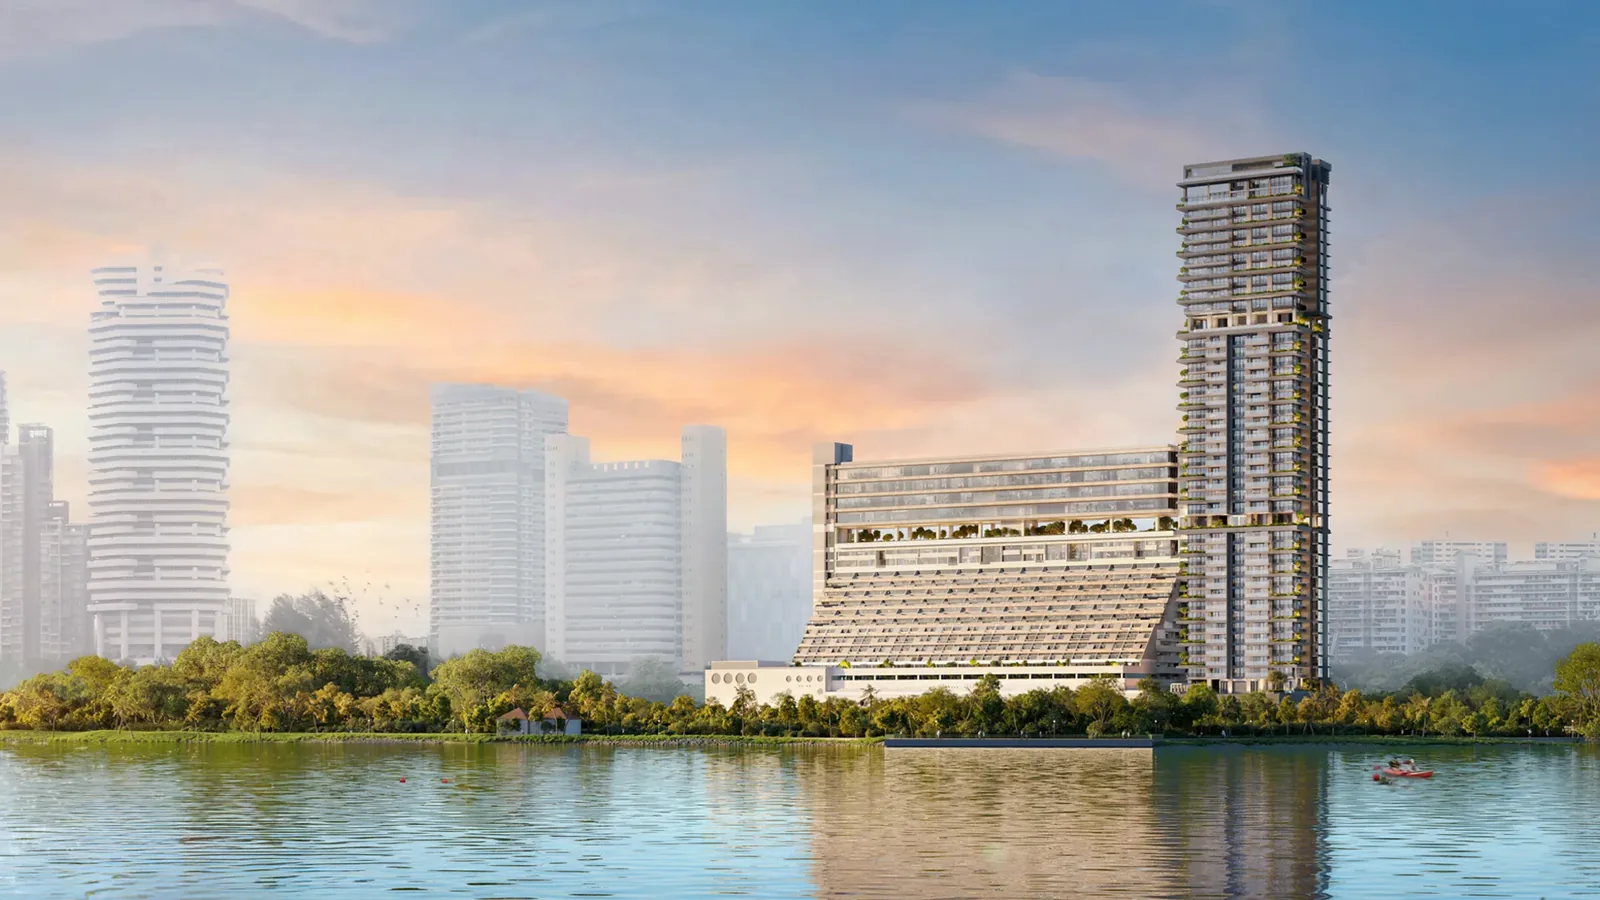
The Short Answer for The Golden Mile
A strata office or medical suite at The Golden Mile is paid for in stages as the building is completed: 20% over the first eight weeks, then construction instalments, 25% at TOP and the final 10% on completion, with 9% GST on each instalment. The bank disburses the loan stage by stage, so interest builds up gradually.
This article walks through the schedule and the cash flow.
The First Eight Weeks at The Golden Mile
The purchase begins with a 5% option fee plus GST on receiving the option to purchase. The Sale & Purchase Agreement is issued to the buyer’s solicitor about two weeks later and must be exercised within three weeks of receipt, at which point Buyer’s Stamp Duty is payable to IRAS within 14 days. By about week eight the balance of the first 20% falls due, again with GST.
At 80% loan-to-value, all of this comes from the buyer’s own funds. On the illustrative $3,000,000 used on this site’s calculators, the cash to secure a unit is $777,600 including GST, Buyer’s Stamp Duty and a $4,000 legal fee.
The Construction Stages at The Golden Mile
After the first 20%, the schedule for commercial property sold under the Sale of Commercial Properties Act runs through foundation and reinforced concrete framework (10% each), then walls, ceiling, doors and windows, electrical, sanitary and air-conditioning works, and car park, roads and drains (5% each). TOP accounts for 25% and completion for the final 10%. The payment scheme page lists each stage.
Where a stage has already been reached when the option is granted, it falls due on exercise; the Sale & Purchase Agreement confirms the position at The Golden Mile.
How the Loan Is Drawn at The Golden Mile
From the foundation stage the bank pays each instalment to the developer, and interest is charged only on the amount drawn so far. The monthly repayment therefore starts small and climbs through construction to the full instalment once the loan is fully drawn. At 90% loan-to-value the bank also funds part of the upfront amount at completion of the sale; at 70%, the later stages revert to cash once the loan is exhausted.
GST on each instalment stays a cash payment throughout. The purchase calculator shows the drawdown, interest and repayment row by row.
A Worked Example at The Golden Mile
Take the illustrative $3,000,000 at 80% loan-to-value. The first 20%, $600,000, plus $54,000 of GST on it, $119,600 of Buyer’s Stamp Duty and a $4,000 legal fee, is paid from the buyer’s own funds within about eight weeks: $777,600 in all. The bank then pays the foundation instalment of $300,000 when that stage is certified, and continues stage by stage until the $2,400,000 loan is fully drawn at completion. GST on each of those instalments is paid by the buyer in cash.
At 90%, the bank also draws $300,000 of the upfront amount at completion of the sale, bringing the buyer’s cash to secure the unit down to $477,600. The figure of $3,000,000 is an illustration, not a unit price.
Questions to Settle Before an Option at The Golden Mile
Before taking an option, a buyer usually confirms three things: the bank’s indicative loan and its letter of offer timing, the purchasing entity and its GST position, and the cash available for the first eight weeks and the GST that follows. With those in hand, the schedule runs smoothly. The stamp duty and GST page and the purchase calculator cover the figures for The Golden Mile.
Because each instalment is billed as a stage is certified, the exact dates depend on construction progress rather than a fixed calendar. The developer’s expected vacant possession date of 30 September 2029 sets the outer frame, and a buyer can plan cash for the early stages with some confidence while keeping a margin for the later ones.
Planning the Cash Flow at The Golden Mile
The developer’s expected vacant possession date is 30 September 2029, and expected legal completion is 30 September 2032. A buyer planning the cash flow therefore needs the upfront sum, the GST on each instalment and the interest during construction; an owner-occupier also needs to allow for rent on existing premises until the move. The commercial loan page explains how banks assess the loan.
Talk to the Sales Concierge About The Golden Mile
The Sales Concierge sends the floor-plan brochure, the current price list and availability for The Golden Mile, and arranges a private sales gallery session.